
-
Most of the A1 tranches, are expected to pay a coupon of 5.83%, except for the A-1 last-cash flow tranche, which is expected to pay 5.93%.
 September 2
-
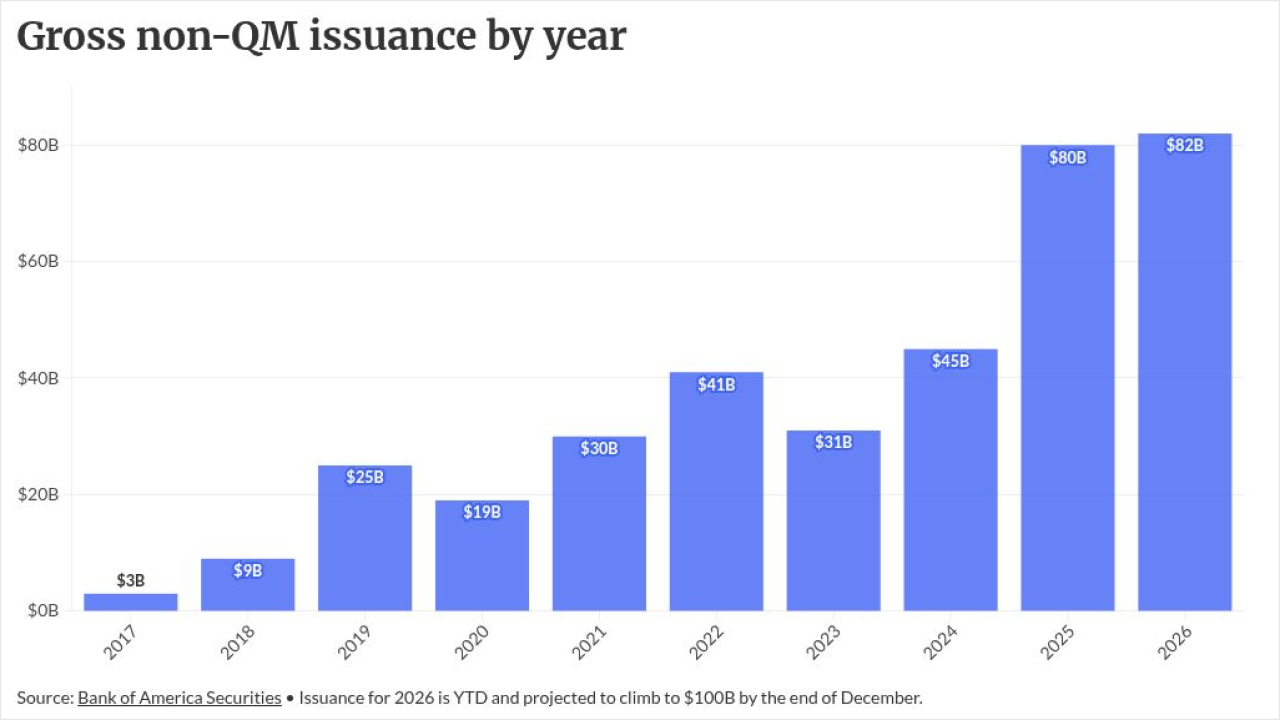
Bank of America Securities research shows this sector has had its best year since at least 2017, but some trends in the market point to a need for caution.
 August 31
-
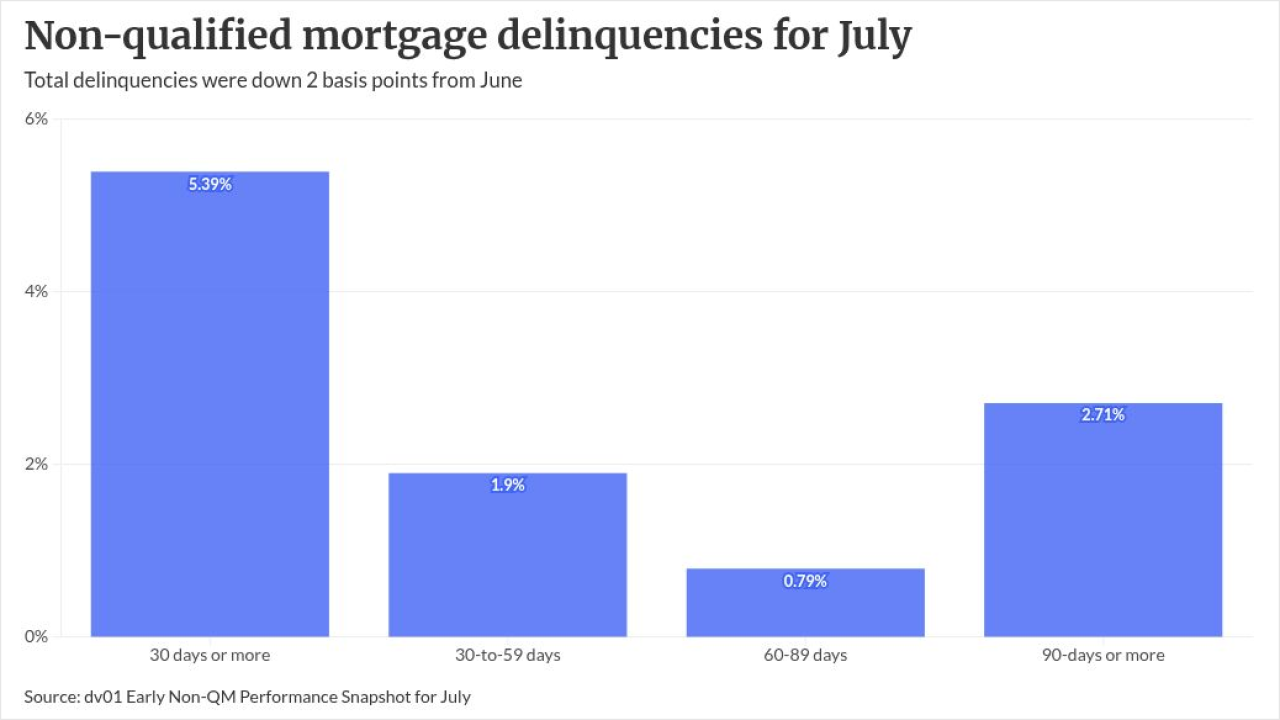
Non-QM securitizations hit $78B as lenders ease guidelines to capture unserved borrower demand, even as total impairments rise for the 10th time in 13 months to 6.27%.
 August 26
-
The product expansion comes at a time when not just non-agency issuance is expected to have a record year, but other lenders are getting into wholesale.
August 25
-
The real-estate investment trust affiliate has been focusing on making more funding available for new loans but also seeks to hold the line on credit quality.
August 4
-
Lenders are still sending files to their secondary market partners with missing or misplaced documents, affecting how the collateral is viewed and priced.
July 22
-
DSCR loans now make up nearly a third of non-QM issuance, but rising rates and thinning yields could expose hidden risk, writes the Chairman of Whalen Global Advisors.
June 22 Whalen Global Advisors LLC
-
Losses stemming from the 2022 vintage have been offset by excess spread, while cure and roll rates signal caution.
April 6
-
Full documentation was only applied to 2.6% of the underlying pool of mortgages. Debt-to-income, however, was 23.3% when it was applied.
March 26
-
Most of the loans, 57.34%, are for cashout purposes and the entire loan pool are first-liens, and are of modest leverage, with an original cumulative loan-to-value (LTV) ratio of 69.74%.
March 24
-
DRMT 2026-INV1, is backed by a pool of 1,153 non-prime investment property mortgages, which have a moderate leverage levels of an original, combined loan-to-value (CLTV) ratio of 69.9%.
January 29
-
The moderate leverage reflects the quality of RMBS pools from recent issuance years. Borrowers have a non-zero WA annual income of $1 million, with liquid reserves of $594,348.
January 23
-
The notes are expected to pay coupons of 4.94% on notes in the A1FCF tranche, rated AAA from KBRA and Fitch Ratings, to 6.78% on the B1 notes.
January 16
-
A significant portion of the loans in the pool by balance, 44.5%, are designated at non-QM, according to DBRS, adding that about 50% of the loans in the pool were made to investors for business purposes.
December 29
-
The terms of NRMLT 2025-NQM7 will not allow it to advance principal and interest on loans that are delinquent by 180 days or more.
December 10
-
If cumulative loss or a delinquency trigger event is in effect, then the deal will distribute principal among the class A notes before any principal allocation the class M1 or class B certificates.
November 26


